






Repairs & Maintenance
Garage Door Damage and Insurance: Questions to Ask Your Insurer

Feb
Reviewed and updated: 14 October 2026
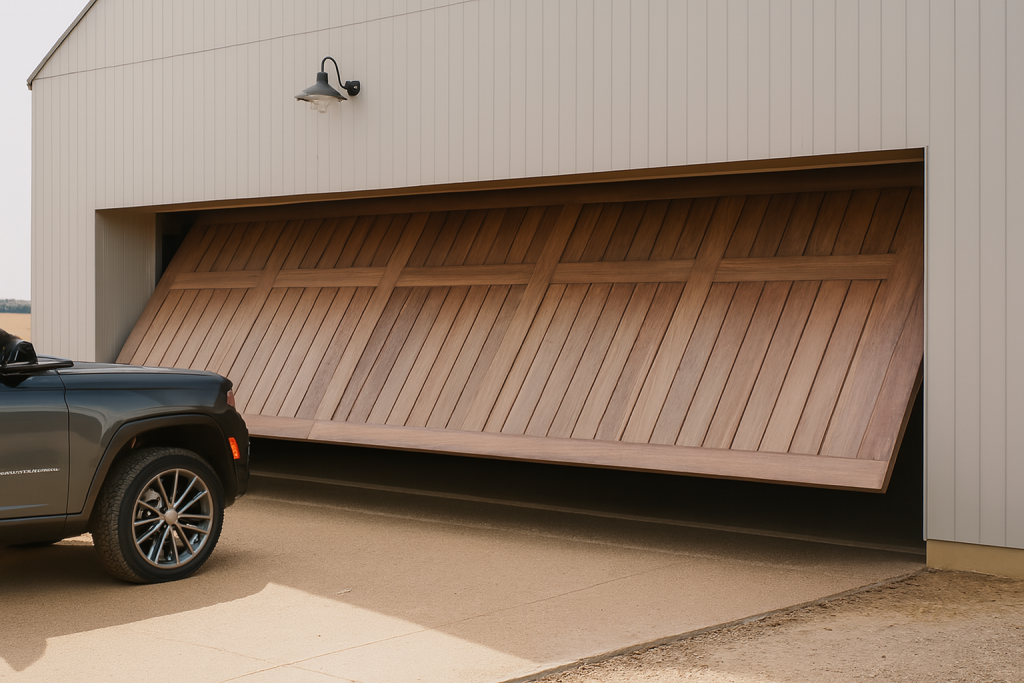
A damaged garage door raises two separate questions: what needs to happen to the door, and whether an insurance policy will pay for it. A repair assessment can address the first. Your insurer must assess the second under the policy and circumstances. Avoid assuming that impact damage, storm damage or an opener fault is covered simply because the garage forms part of the home.
Deal with the physical hazard first
Stop using a door that is bent, uneven, partly raised or behaving unpredictably. Keep people and vehicles away from its movement area. Do not push a damaged panel straight, release the opener, tighten hardware or attempt to secure the door with improvised supports. An insurance enquiry does not require you to demonstrate the fault by operating it again.
Explain the current position when seeking professional advice. Tell the service provider if the garage gives direct access to the home or contains a vehicle that cannot be reached safely. Discuss urgent access and security concerns with the insurer as well. Ask how necessary temporary work is to be arranged and authorised before incurring costs where it is practical to do so.
Identify the relevant policy and event
Locate the policy schedule and Product Disclosure Statement that applied when the incident occurred. Check how the policy describes the insured building, covered events, exclusions, limits and excess. ASIC’s Moneysmart guide to home insurance explains why these details matter. A policy name or general marketing statement is not enough to decide a particular garage-door claim.
Ask the insurer which policy section it considers relevant. Describe what happened rather than assigning it to a type of cover yourself. If a vehicle was involved, provide the facts and let the relevant insurer explain the process. Do not assume that either a home policy or a motor policy must respond. Where the property is rented or part of a shared building, confirm who holds the relevant insurance and who can authorise work.
Keep observations separate from conclusions
Write down when the damage was noticed, the event you actually witnessed and the door’s condition afterwards. Distinguish a known fact from an uncertainty. If the door was found damaged after a storm but nobody saw the impact, say that. A factual description is more useful than changing the story to match a cause you think the insurer expects.
Photograph the overall door and visible damage from a safe position. Keep existing service records, receipts and any relevant incident information together. Do not climb, remove covers or reach into the mechanism to gather evidence. Ask what further information is needed rather than making the door move for a video. Moneysmart’s claims guidance recommends contacting the insurer promptly and retaining your own record of the damage.
Ask about approval before treating a quote as an instruction
Clarify whether the insurer wants an assessment, a quotation or particular documentation, and whether it uses nominated repairers. Ask what freedom you have to choose a repairer and what approval is required before work begins. A quotation from Eastern Garage Doors does not itself establish insurance cover or confirm that the insurer has agreed to pay.
Record the claim reference, contact arrangement and the next action requested. Keep technical findings from a door assessment alongside the insurer’s correspondence, but do not treat them as interchangeable. A technician may describe damaged components and proposed work; the insurer considers the claim. If something is unclear, ask which document or decision is still outstanding before committing to the next stage.
Read the repair scope against the actual damage
Check what the proposal says about the door, opener, controls, removal and related work at the opening. Ask which items would be retained and which would be replaced. If the frame, surrounding wall or electrical arrangement also needs attention, identify who is assessing that work. A garage-door quote should not be assumed to include every building task arising from the same incident.
If the household wants a different colour, a new design or additional access features, keep those preferences visible as separate requests. Ask how any difference between reinstatement and optional improvements will be handled. This avoids comparing a basic repair scope with a broader renovation proposal as though both describe the same job. Keep revised documents when a scope changes.
Understand a cash offer before accepting it
A cash settlement can mean that you take responsibility for organising the relevant repairs. Moneysmart’s cash-settlement guidance highlights the risk that the payment may not cover the cost you actually face. Ask for the calculation and inclusions, compare the proposed work with relevant quotes and understand what remains your responsibility.
Consider the practical work of arranging trades, dealing with uncovered items and managing any further damage discovered. Ask the insurer about available alternatives and the review process if the amount or scope is unclear. You do not need to accept an offer merely to end an uncomfortable conversation. Seek independent advice if you need help understanding the financial or legal consequences for your circumstances.
Keep the claim and repair records together
Retain the agreed scope, authorisations, invoices and the door’s operating information once the matter is resolved. If a new Merlin opener is supplied, keep its model and manual separately identifiable from the door records. That file will help with future service enquiries without requiring you to reconstruct which parts were affected by the original event.
For an assessment of the damaged garage door, contact Eastern Garage Doors. Confirm insurance cover and any claim authorisation directly with your insurer.